
Life expectancy and FIRE: Are You Waiting Too Long to Retire?

My dad celebrated his 80th birthday a few days ago. Eighty years old is a pretty big milestone, and it got me thinking about something slightly uncomfortable:
How many years does he have left?
And maybe more importantly…
How many do I have left?
I know—it’s a morbid thought. But when you have aging parents and a lot of time to think, mortality tends to sneak into your brain whether you invite it or not.
That curiosity led me down a rabbit hole researching life expectancy. I wanted to know whether retiring before 50 was the right move.
And while I was at it, I wondered about my dad’s choice to work until age 70.
For you, if you're pursuing FIRE (Financial Independence, Retire Early), understanding life expectancy and healthy life expectancy becomes surprisingly important.
LIFE EXPECTANCY IN THE UNITED STATES
I’m guessing you don’t consider yourself to be average. We all want to believe we’re extraordinary in something—sports, intelligence, or whatever—because average is just…well…nothing special.
When it comes to life expectancy, most of us assume we’re above average.
Average is for other people, right?
The problem is that averages include everyone—including the unlucky folks pulling the curve down. And statistically speaking, that person could be you or me.
According to the National Center for Health Statistics, the average U.S. life expectancy is about 79 years.
Women average 81.4 years, while men average 76.5 years.
So if you’re a guy like me… congratulations, we drew the short straw.
LIFE EXPECTANCY BY AGE
I pulled data from the Social Security Administration that shows the average number of years you can expect to live at any given age. The most recent data was from 2022, when life expectancy was a year or two lower.
Men born in 2022 could expect to live until about 75. And women could potentially live until 80.
Something interesting happens with life expectancy as you age.
The longer you live, the longer your remaining life expectancy becomes.

That sounds backwards, but it makes sense. Every year you survive means you avoided the risks that kill some people earlier in life.
For example, a 25-year-old man today has an average life expectancy of 51 more years.
The first 50 years are what you might expect. As age increases, the remaining life expectancy slowly creeps up. Meanwhile, the probability of living until a certain age (Percentage alive) decreases.
Things get interesting starting at age 51.

A 51-year-old man can expect to live another 28 years. Women can expect almost another 32 years.
But take a look at what percentage of people make it to that age. One in 10 men won’t make it to their 51st birthday.
Age 51 is still considered relatively young, yet there’s a 10 percent chance you might not make it.
Women are a little more fortunate. They have roughly another 10 years before seeing the same dropoff. Going forward, we’ll focus mainly on men’s life expectancies since we pulled the short stick.
Now look at ages 62, 67, and 70.

Those aren’t random numbers. They’re the three major Social Security milestones:
62 – earliest claiming age
67 – full retirement age for people born in 1960+
70 – maximum delayed benefit
In other words, these are the ages society quietly nudges us toward retiring.

About 19% of men won’t make it to age 62. In the eleven years from age 51 to 62, the probability that a man dies goes from 10% to 19%.
Another five years (age 67), and that percentage jumps up to almost 25%. Then, just three years later (age 70), it’s 30%!
But these numbers are just averages, and you’re not average, are you?
THE RISK OF WAITING UNTIL “NORMAL” RETIREMENT
Many people have it in their minds that they’ll retire sometime between the ages of 62 and 70. Society has deemed this the “normal” retirement age range.
But look at the risk of following the norm.
Imagine you worked until 67 and finally retired. To celebrate, I hand you four shot glasses. One of them contains deadly poison. You only have to drink one.
That’s roughly the same odds as the 25% chance a man doesn’t make it to 67.
Feeling lucky?
Personally, the thought of working my butt off until age 67 with a 25% chance of not getting to enjoy another year of life is a little too risky. Even at age 51, I don’t love that 10% probability, but it’s not horrible.
The data seems to suggest that you’re rolling the dice by waiting until the “normal” age to retire.
Oh, but I forgot. You’re an above-average person. You’re going to beat the odds and will still be alive beyond 67.
There’s just one thing—living and being alive are two different things.
HEALTHSPAN VS LIFESPAN: THE YEARS THAT ACTUALLY MATTER
Until now, we’ve focused on life expectancy. But there’s another number that matters even more than life expectancy.
Healthy life expectancy.
This is the number of years you can expect to live without serious disease or disability.
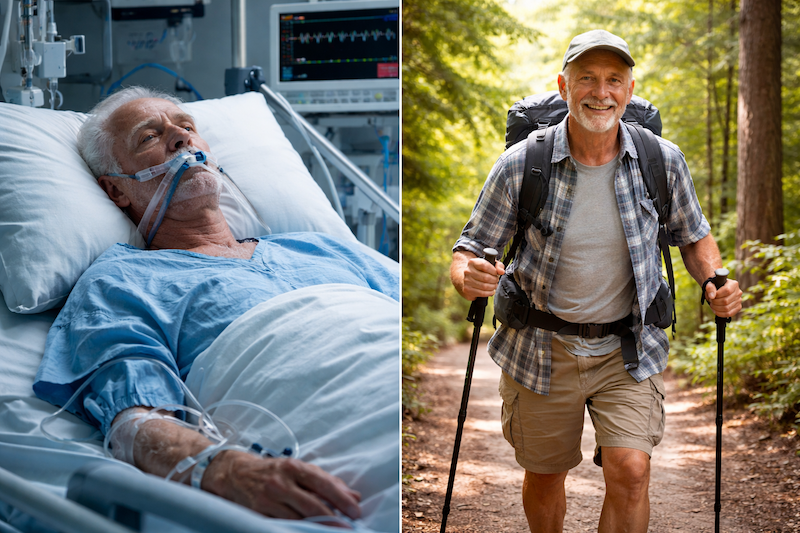
Because technically, being alive and actually living are two very different things. A person hooked up to life support, for example, is medically alive, but nobody would call that living.

According to World Health Organization estimates, the average American enjoys about 66 healthy years, compared to 77.5 total years of life.

So, if you choose to retire at 67, it’s possible you’ll spend the remainder of your life in poor health—alive but not fully living life.
WHAT MY DAD AND UNCLE TAUGHT ME ABOUT RETIREMENT
My dad chose to delay retirement until age 70.
It wasn’t because he loved his job. Trust me—he didn’t. During those final years he looked like a marathon runner crawling across the finish line.
His motivation was simple: maximize his Social Security benefit.
Granted, by delaying his retirement, he increased his benefits by 32%—a substantial amount. The thing is, though, he didn’t need that extra money.
With his military pension and government pension, he would’ve have more than enough to cover living expenses. But for my dad, it was never enough. He wanted every last penny he was entitled to.
So he waited until 70 to begin enjoying retirement. But within three years, major physical disabilities started to raise their heads all at once. He can’t even enjoy that extra money he waited for.
On the other end of the spectrum was my uncle. Like my dad, he also worked for the military and the government. But he chose “early” retirement at age 62.
At the time, I remember my dad commenting about how my uncle won’t even receive his full Social Security benefits. Still, my uncle had enough to live a modest retirement.
Like my dad, my uncle’s retirement was also hampered by medical issues. But he was able to physically enjoy life for more than 10 years first.
RETIREMENT TIMING IS A RISK-REWARD DECISION
For me, it’s obvious who came out ahead. Of course, it could’ve turned out completely differently for my dad. He could’ve retired at 70 and still had 10 healthy years.
But the dice didn’t roll in his favor.
Seeing how their individual choices played out helped lead me to my own choice to retire before 50. It’s possible I could kick the bucket or become physically disabled within a few years. Nobody knows what could happen, so I wanted to stack the odds in my favor as much as possible.
I shared this data and personal stories to help you make your own choice. This is one of the biggest debates in the FIRE community: retire early and accept financial risk, or work longer and risk losing healthy years.
I don’t regret my choice to quit my job for the FIRE life. For me, work was always just a means to provide the life I wanted to enjoy. I worked to live—not the other way around.
But maybe you’re the opposite, and working brings you immense joy. Good for you. But have you ever heard of someone on their deathbed wishing that they had worked more?
Striving for FIRE comes with risk. But so does playing it safe.
Nowhere does it say you must retire at the “normal” age like the average person. And there’s certainly no guarantee you’ll be blessed with the full average life span to enjoy it.
But then again…
you’re not average, right?
See you at the finish line!
Disclaimer: I’m not a licensed financial professional. This blog shares my personal experiences and opinions around money, investing, and early retirement. It’s for informational and educational purposes only—not financial, legal, or tax advice. Always do your own research or consult with a qualified professional before making any financial decisions.


Comments